A High Backlog Can Hide Financial Risk in a Construction Company
Backlog is contracted revenue still to be performed — it is not cash, not profit and not financial capacity. A growing backlog can strengthen a contractor or increase its capital requirement, client concentration and execution risk. The CEO needs to measure the financial quality of the backlog, not just its size.
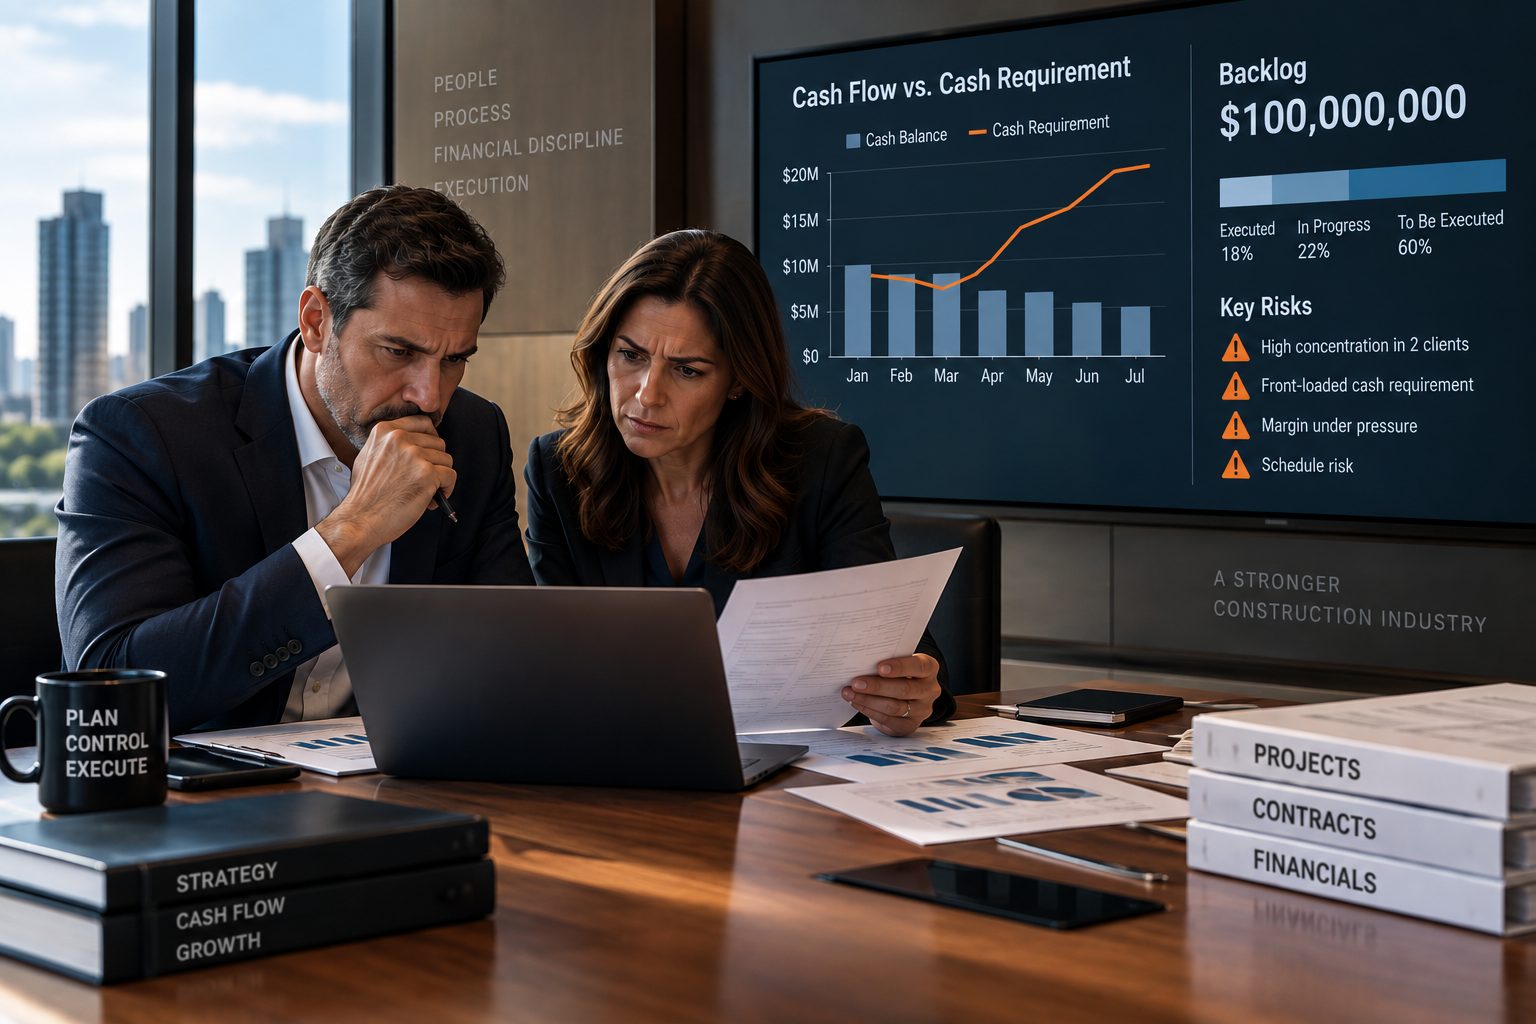
“Our backlog has never been this full.” Few sentences sound better in a board meeting. For business development, it is proof that the company has won market share. For finance, it may be the start of a period of pressure: every signed contract brings future revenue, but also mobilizations, purchasing, payroll, retainage and payment cycles that will have to be financed before they turn into cash.
The same backlog can be excellent commercial news and a financial warning at the same time. A construction company’s backlog shows how much it has sold and still has to build. On its own, it does not show how much capital that work will consume, how much profit it will actually generate, or how much risk is concentrated in a few clients or a few months.
This is the fourth article in a series on contractor financial management. In the first, we showed why growth can consume a contractor’s working capital. In the second, we explained how to calculate the maximum cash required for a new project before signing the contract. In the third, we presented the 13-week cash flow forecast, which reveals when cash will come under pressure. Now the question widens: what is the future financial load of the entire portfolio already under contract?
The progression is direct: growth consumes capital; every project has a maximum capital requirement; the 13-week forecast shows the timing of that requirement in the near term; and backlog analysis shows the size and shape of the financial load still to come.
What backlog is in construction — and what it is not
Backlog is the contracted value not yet performed. In construction, it is the portion of signed contracts whose work — and therefore whose revenue — has not yet been earned. It is also called contracted work or remaining performance obligations in some reporting contexts. The exact measurement and revenue recognition criteria follow applicable accounting standards and company policy; the reading proposed here is a management view.
To avoid common confusion in the boardroom, it helps to separate five concepts that tend to appear together:
- Backlog (contracted work): contracted revenue still to be performed. It is a promise of future production, conditional on execution, change orders, payment applications and the owner’s performance.
- Billings: what has already been submitted to and invoiced to the owner through payment applications. Billings may run ahead of or behind earned revenue.
- Revenue: what has been recognized in the income statement as work is performed, under applicable accounting criteria.
- Accounts receivable: what has been billed and not yet paid — including contract retainage that will only be released later.
- Cash: money actually available, free of restrictions, to pay payroll, suppliers, taxes and debt.
In other words: backlog is not cash, it is not profit and it is not financial capacity. It is an obligation to perform that, if well priced and well financed, will turn into revenue, margin and, last of all, cash. Between signing and the final collection, the company has to carry the work.
Why “$100 million in backlog” says little about financial health
A backlog figure answers a commercial question: how much has been sold? It does not answer the questions a CEO needs to ask before celebrating. How much of this backlog goes into execution in the next six months? What margin remains after risks and escalation? How much will the owner hold in retainage until completion? Who pays, how quickly and with what concentration?
Two contractors with the same backlog can be in opposite situations. One may have a backlog that strengthens cash over time. The other may have a backlog that, even if profitable on paper, requires more capital than the company has. The total value hides exactly the variables that determine that difference.
Backlog quality: the concept missing from the board meeting
Backlog quality is the ability of contracted work to convert into margin and cash within the company’s financial and operational limits. A high-quality backlog combines reliable margin, execution spread over time, compatible payment terms, diversified clients, controlled contract risk and available operational capacity.
In the Elevare methodology, we treat this reading as an experimental lens called Backlog Quality™. It is not a market standard, a regulatory index or an accounting standard. It is a structured way to ask the right questions about the backlog before the answers show up in the bank balance.
The 7 dimensions of backlog financial quality
1. Expected margin and the quality of that margin
Budgeted gross margin is the starting point, not the conclusion. The question is how much of that margin is supported by contracted price and controlled cost, and how much depends on unapproved change orders, uncertain escalation, productivity above historical levels or buyouts not yet closed. An 11% margin in which 3 points depend on pending claims is, in practice, a firm 8% margin with an upside option.
2. Execution schedule and timing concentration
A backlog spread over 24 months is very different from a backlog that almost entirely starts in the next six. Timing concentration defines peak production, purchasing and payroll — and therefore peak capital. The same contracted value can represent a manageable ramp or an abrupt step.
3. Cash curve and capital requirement
Every project has its own cash curve, with a largest cumulative deficit before it becomes cash-generating. Added together, these curves form the portfolio cash requirement. Contracts with heavy mobilization, slow payment applications or suppliers on short terms deepen that deficit. Backlog without a cash curve is a volume; with a cash curve, it becomes a measurable capital requirement.
4. Payment terms, retainage and advances
Billing cycle, approval time, payment terms, retainage percentage and the existence of advance payments are the variables that most turn revenue into capital requirement. Retainage of 10% on $72 million of work performed ties up $7.2 million until release. A contractual advance of 3%, by contrast, finances part of the mobilization.
5. Client concentration
When three clients account for the entire backlog, an approval delay, a payment application dispute or financial difficulty at a single owner affects a significant share of future inflows. Concentration is not necessarily a mistake — large contracts can be strategic — but it needs to be measured and offset with liquidity.
6. Contract risk, escalation and change orders
Lump-sum contracts with little protection against material escalation, poorly defined scope, significant liquidated damages or dependence on change orders to restore margin increase the variance of the outcome. That variance has a cash effect: claims take time to negotiate, and the related work is usually paid for first.
7. Operational capacity required to perform
Backlog requires people: field crews, project managers, superintendents, foremen, equipment and qualified subcontractors and suppliers. If the backlog assumes three simultaneous mobilizations with teams that do not yet exist, the risk is not only operational: delays and rework extend general conditions, push back billings and deepen the capital requirement.
Hypothetical example: two contractors, the same $100 million backlog
The figures below are hypothetical and illustrative, simplified to show the logic. They do not represent real companies and are not industry benchmarks. Both contractors have $100 million in backlog and $10 million in available cash.
- Company A: 8 contracts with 6 clients; the 3 largest clients represent 38% of the backlog. Expected gross margin of 14%, with no dependence on pending change orders. Staggered mobilizations: 36% of the backlog ($36 million) goes into execution in the next 6 months. Average cycle between work performed and collection of 60 days, 5% retainage and a 3% contractual advance. Supplier and subcontractor terms averaging 45 days.
- Company B: 3 contracts with 3 clients, of $50, $30 and $20 million; the 3 largest clients represent 100% of the backlog. Budgeted gross margin of 11%, of which 3 points depend on unapproved change orders. Simultaneous mobilizations: 72% of the backlog ($72 million) goes into execution in the next 6 months. Average cycle of 75 days, 10% retainage and no advance. Supplier and subcontractor terms averaging 30 days.
To estimate peak capital exposure over the next six months, we use a simple management approximation, valid only for this example: receivables in cycle + accumulated retainage − advances received − supplier and subcontractor financing. We assume that 60% of monthly production corresponds to supplier and subcontractor costs. A real analysis should build the curve month by month, project by project.
- Average monthly production: A, $36 million ÷ 6 = $6.0 million; B, $72 million ÷ 6 = $12.0 million.
- Receivables in cycle (monthly production × cycle in months): A, $6.0 million × 2.0 = $12.0 million; B, $12.0 million × 2.5 = $30.0 million.
- Retainage accumulated over 6 months: A, 5% × $36 million = $1.8 million; B, 10% × $72 million = $7.2 million.
- Advances received: A, 3% × $100 million = $3.0 million; B, zero.
- Supplier and subcontractor financing (monthly production × 60% × terms in months): A, $6.0 million × 0.6 × 1.5 = $5.4 million; B, $12.0 million × 0.6 × 1.0 = $7.2 million.
- Estimated peak capital requirement: A, 12.0 + 1.8 − 3.0 − 5.4 = $5.4 million; B, 30.0 + 7.2 − 0 − 7.2 = $30.0 million.
- Headroom over available cash of $10 million: A, +$4.6 million; B, −$20.0 million.
Now compare what each backlog delivers and demands:
- Total backlog: A, $100 million; B, $100 million.
- Expected gross margin: A, 14% ($14 million), fully contracted; B, 11% ($11 million) budgeted, of which $3 million depends on change orders — a firm margin of 8% ($8 million).
- Estimated peak capital requirement: A, $5.4 million; B, $30.0 million — more than five times A’s.
- Capital requirement relative to firm margin: A, $5.4 million for $14 million of margin (0.39); B, $30.0 million for $8 million of firm margin (3.75).
- Top 3 client concentration: A, 38%; B, 100%.
- % of backlog going into execution in the next 6 months: A, 36%; B, 72%.
The backlog is identical. The economic value and the risk are not. Company A has a backlog that fits within its own cash, with reliable margin and diluted risk. Company B needs to find an additional $20 million — through credit, equity, renegotiation or a slower pace — to perform a backlog whose firm margin is lower and whose collections depend on only three clients. If one of them pays late, the requirement grows precisely when the company is most exposed.
Company B is not necessarily making bad deals. Its contracts may be strategic and profitable over the long term. The point is that the same backlog figure represents, for it, a much larger capital requirement — and that needs to be decided deliberately, not discovered in the middle of execution.
Commercial backlog versus financial backlog
We propose a management distinction — not an accounting one — between two readings of the same backlog. It does not replace the accounting definition of backlog, performance obligations or revenue recognition; it complements the commercial view with a capital view.
- Commercial backlog: contracted value still to be performed. It answers: how much have we sold and still need to build?
- Financial backlog (Elevare management lens): the same backlog read through firm margin, cash curve, peak capital requirement, client concentration and execution schedule. It answers: how much is this backlog economically worth, how much capital does it require, and when?
In the example, the commercial backlog of the two companies is the same. The financial backlog is radically different. A leadership team that tracks only the first is deciding blind about the second.
Backlog and Project & Portfolio Capital Requirement™
Project & Portfolio Capital Requirement™, presented in this series as an experimental lens, estimates how much capital a project or a portfolio requires and where the largest cumulative deficit between disbursements and collections occurs. Backlog analysis applies that logic to the contracted portfolio: it adds up the cash curves of the projects already signed, considering mobilization dates, payment terms, retainage and advances.
The result answers the question a backlog figure does not: how much capital does the company need to have available to perform what it has already sold? And, as a consequence: how much room is left to sign the next project?
What the 13-week forecast does not see — and backlog does
The 13-week Cash Flow Forecast™ shows near-term cash timing precisely: weeks, specific collections, due dates, the lowest projected balance. It is the right tool for deciding what to do in the coming weeks. But, by definition, it ends at week 13.
A major mobilization scheduled for month 5, a large contract reaching peak production in month 8 or retainage released only in month 14 fall outside that horizon. Backlog analysis anticipates that load beyond 13 weeks. The two readings are complementary: backlog shows the size and shape of future pressure; the 13-week forecast shows when it reaches cash and demands a decision.
The 6 numbers the CEO should see alongside backlog
- 1. Total backlog: contracted value still to be performed. It is the starting point, never the conclusion.
- 2. Expected gross margin in backlog: in dollars and percentage, separating the firm portion from the portion that depends on change orders, escalation or claims not yet approved.
- 3. Consolidated peak capital requirement: the largest cumulative deficit of the combined cash curves of contracted projects, compared with available cash and credit lines that are actually accessible.
- 4. Top 3 client concentration: the share of the backlog dependent on a few payers.
- 5. Weighted average payment cycle or collection exposure: the value-weighted average time between work performed and cash, including the effect of retainage.
- 6. Percentage of backlog going into execution in the next 6 months: the speed at which the backlog will put pressure on production, purchasing and cash.
In the example, these six numbers tell opposite stories for the same $100 million backlog. None of them requires a sophisticated system; they require business development, operations and finance to look at the same backlog with the same assumptions.
Warning signs in the backlog
- Backlog grows faster than liquidity: the backlog doubles, but cash and available credit lines stay the same. The capital requirement grows without a defined source.
- Mobilizations are concentrated: several projects start in the same quarter, stacking peaks in purchasing, payroll and general conditions.
- Margin depends on unapproved change orders: budgeted profit is only confirmed if claims under negotiation are accepted — and the related cash will arrive late.
- A few clients account for a large share of the backlog: an approval or payment delay affects a significant share of future inflows.
- Supplier and subcontractor terms are shorter than owner payment terms: the company finances the gap with its own cash every month of production.
- The company repeatedly uses short-term debt to finance production: credit stops covering occasional mismatches and starts structurally carrying the backlog.
Governance: how the backlog should be reviewed
Backlog quality is not the responsibility of a single function. We recommend a monthly backlog review among business development, operations and finance, with one official version of the six numbers and the assumptions for each project.
- Business development: presents signed contracts and those under negotiation, payment terms, advances, retainage and escalation clauses.
- Operations: confirms schedules, mobilizations, available teams and execution risks that affect time and cost.
- Finance: consolidates cash curves, peak capital requirement, client concentration and available financing sources.
- CEO: decides priorities, pace of growth and exposure limits, with the consolidated portfolio in view.
The central rule is simple: no new project enters the backlog without explicit margin, operational capacity and cash assumptions. Before signing, the question is not only whether the contract is profitable, but whether the portfolio — with that contract included — still fits within the company’s financial and operational limits.
Backlog, Capital Capacity™ and Cash Flow Forecast™
In the Elevare methodology, backlog quality analysis connects to the Capital Capacity™ dimension: the organization’s capacity to financially sustain its strategy and its portfolio. Cash Flow Forecast™ tracks the near-term horizon; backlog reading and Project & Portfolio Capital Requirement™ extend the view to the load already under contract. Together, they help leadership grow within known limits, instead of discovering those limits during execution.
A full backlog is an achievement. A full backlog without a financial reading is a bet. The difference between the two lies in measuring backlog quality with the same discipline used to measure its value.
If all contracted work starts executing at the planned pace, how much additional capital will the company need before that backlog turns into cash?
Answer it by adding up the cash curves of contracted projects, with real mobilization dates, payment terms, retainage and advances, and comparing the largest cumulative deficit with available cash and credit lines that are actually accessible. If the answer is unknown, the first risk has already been identified.
To assess how contracted backlog, capital requirements and execution capacity connect in your construction or development company, explore the Elevare™ Organizational Capability Assessment.
Renato Lerner
Founder, Elevare™
Renato Lerner has 30 years of experience in construction in Brazil, Angola, and the United States. He is the founder of Elevare™ and creator of the Organizational Capability Diagnostic.