Estimated vs. Actual Construction Margin: Where Project Profit Disappears
A project rarely loses its margin all at once at closeout. Margin is consumed throughout execution by small, recurring variances — productivity, procurement, rework, schedule, general conditions, scope and late decisions. The problem is when the contractor only finds out at project closeout.
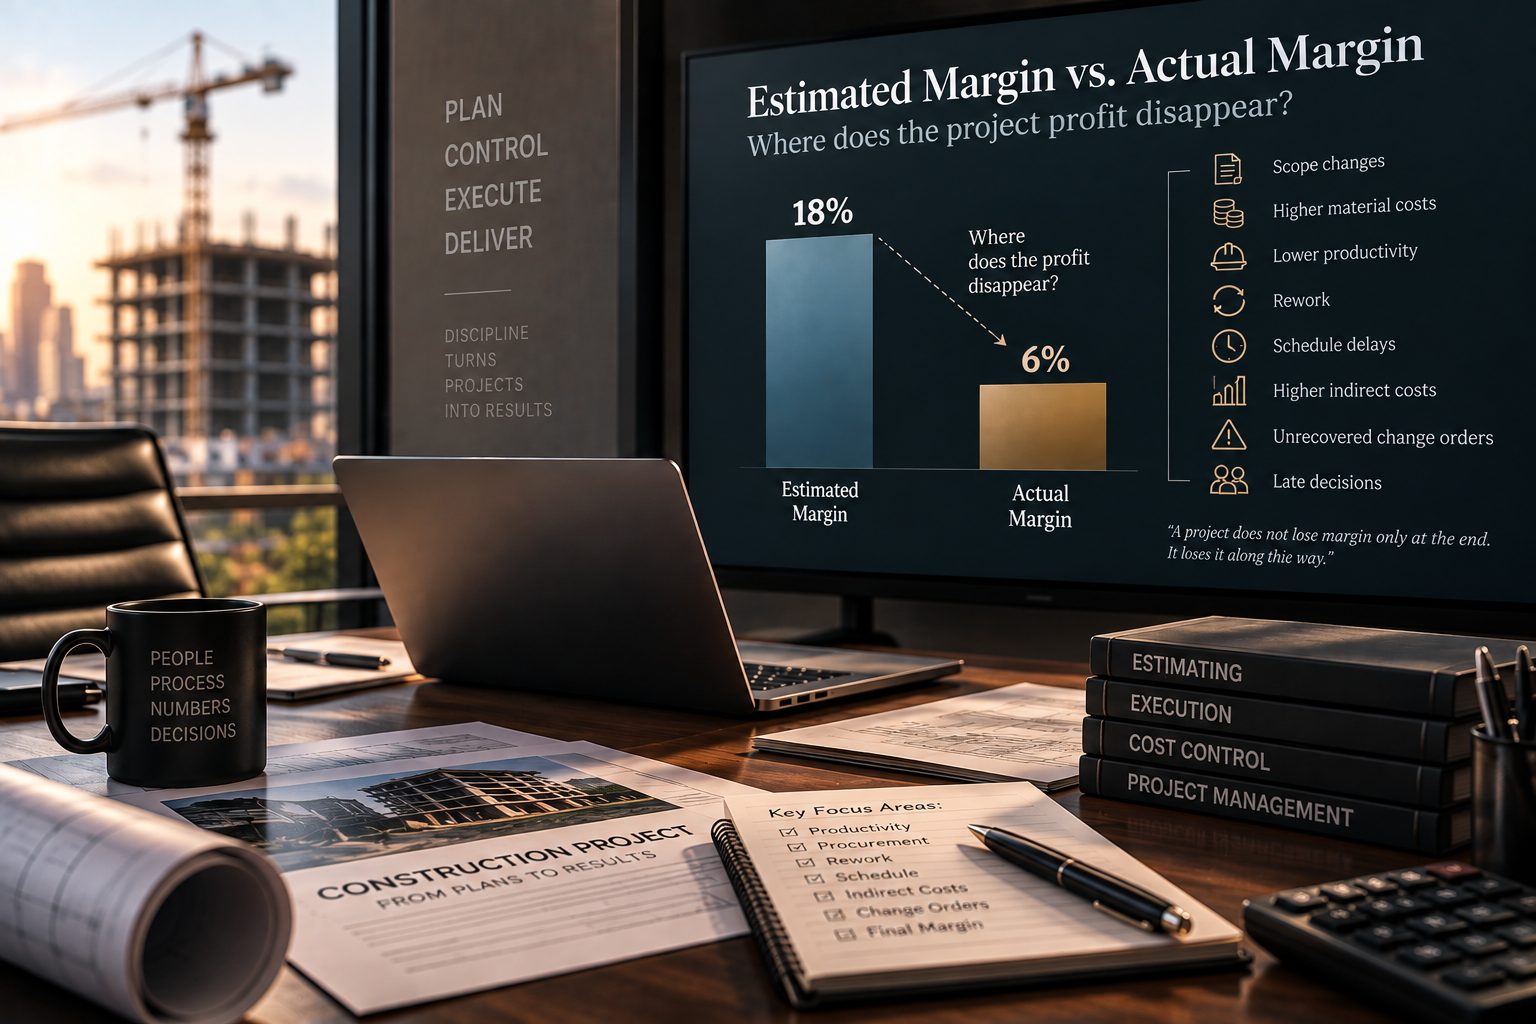
A project bid at an 18% margin can finish at 6% without a single “major disaster.” There was no serious accident, no termination, no owner who stopped paying. What happened, month after month, was a crew slightly less productive than estimated, a steel order slightly more expensive, a section torn out and rebuilt, three extra months on site, a design change performed without a signed change order, and a decision made too late.
Each variance, on its own, looks too small to reach the CEO’s desk. Added together, they consume two-thirds of the project’s profit. And the worst part is not the loss itself: it is discovering it only at closeout, when there is nothing left to do except explain the result.
This is the fifth article in a series on contractor financial management. We have shown why growth can consume working capital, how to calculate the maximum cash a new project requires before signing the contract, how a 13-week cash flow forecast anticipates pressure on cash, and why a high backlog can hide financial risk. The progression now reaches execution: capital, cash requirements, forecast and backlog only hold up if each project’s margin is preserved while it is being built.
Estimated margin, current forecast margin and actual margin
Construction project margin is the difference between contract revenue and the total cost to deliver the contract. The problem is that there are three versions of that margin, and each answers a different question:
- Estimated (bid) margin: the margin estimated when the contract is signed — contract value minus budgeted cost. It answers: how much did we expect to make when we signed?
- Current forecast margin (forecast at completion): the margin the project is expected to deliver at the end, recalculated periodically from cost already incurred plus the best estimate of the cost remaining. It answers: how much will we make if current trends continue?
- Actual margin: the margin actually determined after project closeout. It answers: how much did we really make?
Accounting terminology can vary across companies, standards and revenue recognition policies. In this article we use a management lens: the goal is not to define how margin is accounted for, but how leadership tracks its evolution in time to act.
Why cost incurred versus budget is not enough
The most common construction cost control report compares what has been spent with the budget. It is necessary, but insufficient: it shows the past and says little about final cost. A project can be “on budget” in every monthly report and still be heading toward a significant loss — all it takes is an underestimated cost to finish.
To truly track margin, the contractor needs two additional numbers:
- ETC (Estimate to Complete): the estimate of the cost still to be incurred to finish the project, based on remaining quantities, actual observed productivity, prices already committed and known risks.
- EAC (Estimate at Completion): the estimated final cost of the project. EAC = cost incurred + ETC. Forecast margin is the current contract value minus the EAC.
Beyond these, committed costs matter — purchase orders and subcontracts already executed but not yet incurred — as do trends: the direction in which productivity, prices and schedule are moving. A project cost forecast is the disciplined combination of these elements.
Hypothetical example: from 18% to 6% without a major disaster
The figures below are hypothetical and illustrative, built to show the mechanism. They are not industry benchmarks or a reference for expected performance.
A contractor signs a $50.0 million contract with a budgeted cost of $41.0 million. The estimated margin is $9.0 million, or 18%. The contract duration is 18 months. No change orders are approved during the project; the current contract value remains $50.0 million.
During execution, six sources of erosion gradually consume the margin:
- Low labor productivity: $1.8 million
- Procurement variance and material escalation: $1.2 million
- Rework: $0.7 million
- Schedule extension and general conditions: $1.0 million
- Design changes and unrecovered scope: $0.8 million
- Late decisions and inefficiencies: $0.5 million
- Total erosion: $6.0 million
The estimated final cost (EAC) rises from $41.0 million to $47.0 million (41.0 + 6.0). Margin falls to $3.0 million, or 6% (3.0 ÷ 50.0). The project lost two-thirds of its expected profit.
How the forecast margin evolves over the project
If the forecast is updated honestly every month, the erosion shows up gradually:
- Contract award: EAC $41.0 million; margin $9.0 million (18.0%)
- Month 4: EAC $41.8 million; margin $8.2 million (16.4%)
- Month 8: EAC $43.5 million; margin $6.5 million (13.0%)
- Month 12: EAC $45.5 million; margin $4.5 million (9.0%)
- Month 14: EAC $47.0 million; margin $3.0 million (6.0%)
- Closeout (month 21): final cost $47.0 million; actual margin $3.0 million (6.0%)
The company that tracks the forecast sees the trend from month 4 and has the complete answer in month 14 — seven months before the end, still with room to negotiate, re-plan and recover. The company that tracks only cost incurred versus budget may discover the same 12 percentage points of loss at closeout.
The Margin Bridge: where the profit disappeared
A Margin Bridge is a simple way to explain the gap between estimated margin and actual margin, cause by cause. In the example:
- Starting estimated margin: $9.0 million (18%)
- (−) Low productivity: $1.8 million → $7.2 million
- (−) Procurement and material escalation: $1.2 million → $6.0 million
- (−) Rework: $0.7 million → $5.3 million
- (−) Schedule extension and general conditions: $1.0 million → $4.3 million
- (−) Changes and unrecovered scope: $0.8 million → $3.5 million
- (−) Late decisions and inefficiencies: $0.5 million → $3.0 million
- Final margin: $3.0 million (6%)
No single cause exceeds 3.6 percentage points of margin ($1.8 million ÷ $50.0 million). That is exactly why the erosion slips through: each item looks manageable; the whole is not.
The 7 sources of construction margin erosion
1. Labor productivity
When the crew produces less per hour than the estimate assumed, every square foot, every cubic yard and every ton costs more. Productivity is usually the largest and least visible driver of loss, because the cost shows up as normal payroll and payroll burden — not as a “variance.”
2. Procurement and materials
Buyout prices above estimated prices, quantities greater than the takeoff, material price escalation and emergency purchases made without negotiation erode margin with every order.
3. Rework
Work performed twice costs twice and generates no additional revenue. Rework comes from quality failures, design conflicts and poor sequencing — and it almost never has its own line in the budget.
4. Schedule and general conditions
Every additional month on site consumes general conditions — project management staff, site facilities, equipment, insurance, security — that do not depend on the volume of work produced. Time is cost.
5. Design and scope changes
Changes requested by the owner or the design team, scope poorly defined in the contract and “small” items performed as a courtesy accumulate cost without the corresponding revenue.
6. Unapproved change orders and unrecovered revenue
A change order under negotiation is not revenue. When the project performs the change before formal approval, the cost is certain and the revenue is uncertain. If the claim is denied, reduced or approved late, margin absorbs the difference.
7. Late decisions and delayed information
A purchase decided late is made without negotiation. A re-plan decided late no longer prevents the delay. Field information that reaches finance 45 days later arrives when the loss has already happened. Slowness in deciding is a cause of erosion in itself.
Profit disappears before it shows up on the income statement
The income statement is a lagging indicator: it records results after they have happened and depends on the revenue recognition method. By the time margin loss is evident there, the causes are usually already in the past.
Leading indicators show the erosion while it can still be contained:
- Actual versus estimated labor productivity, by critical activity (hours per unit installed).
- Buyout price versus estimated price, on every significant order.
- Field quantities versus estimated quantities.
- Physical progress versus schedule, and the impact of each month of delay on general conditions.
- Volume of changes performed without an approved change order.
- Rework hours and costs, recorded as such.
- Monthly evolution of EAC and forecast margin.
A leadership team that tracks only lagging indicators manages the result; one that tracks leading indicators manages the margin.
The 6 numbers the CEO should see every month, project by project
- 1. Original contract value: the signed revenue base.
- 2. Approved change orders: only those formally approved by the owner; pending claims are kept separate.
- 3. Current contract value: original + approved change orders.
- 4. Cost incurred: cost actually incurred to date.
- 5. ETC (Estimate to Complete): the estimated cost remaining to finish.
- 6. EAC and forecast margin: EAC = incurred + ETC; forecast margin = current contract value − EAC.
We recommend adding a seventh number, committed costs: purchase orders and subcontracts already executed that have not yet become incurred cost. They show how much of the ETC is already “locked in” on price and how much still depends on future buyout.
In the example, at month 14: original contract value $50.0 million; approved change orders $0; current contract value $50.0 million; cost incurred $33.1 million; ETC $13.9 million; EAC $47.0 million; forecast margin $3.0 million (6%).
Budget × Committed × Actual × Forecast
The most useful executive view places side by side, by cost group: the budget, the amount already committed, the cost incurred (Actual) and the estimated final cost (Forecast/EAC). In the example, at month 14 ($ millions):
- Self-performed labor: Budget 9.0 · Committed — · Actual 8.1 · Forecast 10.8 (variance +1.8)
- Materials: Budget 14.0 · Committed 13.9 · Actual 10.9 · Forecast 15.2 (variance +1.2)
- Subcontractors: Budget 10.0 · Committed 10.7 · Actual 7.8 · Forecast 11.5 (variance +1.5: rework 0.7 + unrecovered scope 0.8)
- General conditions: Budget 6.0 · Committed — · Actual 4.7 · Forecast 7.0 (variance +1.0)
- Equipment and other: Budget 2.0 · Committed — · Actual 1.6 · Forecast 2.5 (variance +0.5: late decisions)
- Total: Budget 41.0 · Actual 33.1 · Forecast 47.0 (variance +6.0)
“Committed” appears only where purchase orders and subcontracts have been executed; for self-performed labor, general conditions and equipment, cost is incurred over time. Note that the Forecast for materials and subcontractors already exceeds the committed amount: there is still buyout to be done, and the ETC must reflect the likely price of that buyout, not the estimated price.
Percent complete and revenue recognition, without an accounting lecture
Many contractors measure progress using cost incurred over total estimated cost (cost-to-cost). Revenue recognition rules depend on the applicable accounting standards and each company’s policies; here we are interested only in the management effect.
In the example, at month 14, cost incurred is $33.1 million. If the denominator is the original budget ($41.0 million), the project would appear 80.7% complete. If it is the updated EAC ($47.0 million), it is 70.4% complete. Using an outdated total cost inflates progress, pulls revenue and profit forward in the report and pushes the loss into the final months — exactly the “the margin collapsed at the end of the job” pattern.
The management lesson: percent complete is only reliable if the EAC is reliable. An optimistic ETC does not just hide cost; it also distorts the results reported throughout the project.
Productivity: how hours turn into margin
Operational productivity converts into financial impact through simple arithmetic: hours earned for the quantity installed versus hours actually spent.
In the example, the self-performed labor budget ($9.0 million) assumed 150,000 hours at an average cost of $60 per hour to install 100% of quantities. At month 14, the project had installed 75% of quantities. Per the estimate, that should have consumed 112,500 hours; 135,000 hours were spent ($8.1 million) — a factor of 1.2 actual hours for every estimated hour.
If that productivity holds, the remaining 25% will consume 45,000 hours (37,500 × 1.2), or $2.7 million. The labor EAC becomes $10.8 million (8.1 + 2.7), $1.8 million over budget. An ETC that assumed a return to estimated productivity would project only $2.25 million to finish — and hide $0.45 million of probable loss.
Procurement: price, quantity and the unit estimate
In procurement, margin is affected by two effects worth separating: the price effect (buyout price versus estimated unit price) and the quantity effect (final quantity versus estimated quantity).
In the example, steel was estimated at 1,200 tons at $5,000 per ton ($6.0 million). It was bought out at $5,500 per ton, and the final quantity reached 1,260 tons: a cost of $6.93 million. The $0.93 million procurement variance splits into a price effect of $0.60 million ($500 × 1,200 tons) and a quantity effect of $0.33 million (60 tons × $5,500). Other materials add $0.27 million of variance, for a total of the $1.2 million shown in the Margin Bridge.
The separation matters because the responses differ: the price effect calls for buyout strategy, earlier purchasing and negotiation; the quantity effect calls for reviewing the takeoff, the design and field waste.
Schedule: every additional month costs twice
In the example, general conditions were budgeted at $6.0 million for 18 months — about $333,000 per month. The project finished in 21 months: three additional months consumed $1.0 million of margin.
A longer schedule also affects cash. Closeout is pushed back, the final pay application arrives later, and retainage — released only at substantial completion or after acceptance — takes longer to come back. If the contract withholds 5% of each pay application, that is $2.5 million held for three months longer than planned. Schedule affects margin and capital at the same time.
Governance: who owns each number
Preserving margin requires a monthly routine and clear owners:
- Monthly update of the final cost forecast for each project: EAC and forecast margin reviewed every month, with one official version.
- Project manager owns the ETC: the people who know the field estimate what remains, based on actual observed productivity — not estimated productivity.
- Procurement validates committed costs: executed purchase orders and subcontracts, prices and remaining buyout.
- Finance reconciles cost incurred: actuals tie to the accounting records and to pay applications.
- The CEO reviews exceptions and margin trends: projects whose forecast margin has fallen, their causes and recovery plans with a deadline and an owner.
The most important rule is cultural: do not allow operational optimism to hide a probable loss. An ETC that assumes recovery without a concrete plan is not a forecast; it is hope. A loss recognized early can be managed; a hidden loss only appears at closeout.
Margin Integrity™: an experimental Elevare lens
We propose Margin Integrity™ as an experimental Elevare concept, not a market standard or an accounting standard. The idea is to assess not only the level of margin but the reliability of the reported number: how much of the forecast margin is supported by observed productivity, committed prices and approved change orders — and how much depends on assumptions not yet confirmed.
Two projects with the same 12% forecast margin can have very different integrity: in one, the ETC reflects actual productivity and 90% of remaining costs are already committed; in the other, the ETC assumes a productivity recovery with no plan behind it and the margin depends on claims under negotiation.
Margin, cash and capacity are not managed in isolation
In the Elevare methodology, margin preservation connects to the Capital Capacity™ dimension: every point of margin lost is capital that no longer funds the next project. The Cash Flow Forecast™ feels the erosion when it becomes higher disbursements or delayed collections; Backlog Quality™ analysis depends on reliable firm margins; and Project & Portfolio Capital Requirement™, as an experimental lens, grows when the EAC rises and the schedule stretches.
A margin that shrinks silently makes the cash forecast optimistic, the backlog less valuable than it appears, and the capacity to grow smaller than leadership believes.
If the project finished today with current trends in productivity, procurement, schedule and scope, what would the final margin be — and when would leadership find out?
If the answer only comes at closeout, the company does not have a margin problem; it has a visibility problem, and it costs margin on every project.
To assess how margin control, cost forecasting and capital capacity connect in your construction or development company, explore the Elevare™ Organizational Capability Assessment.
Renato Lerner
Founder, Elevare™
Renato Lerner has 30 years of experience in construction in Brazil, Angola, and the United States. He is the founder of Elevare™ and creator of the Organizational Capability Diagnostic.